
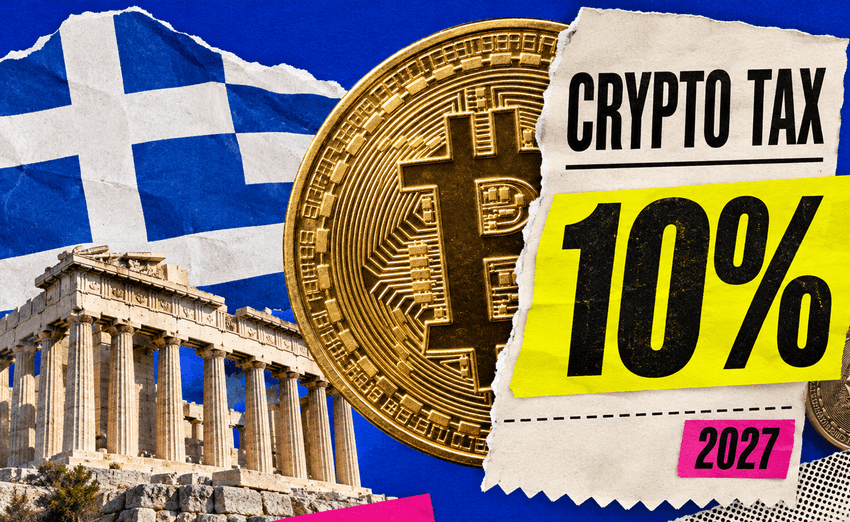
Greece's parliament has approved a new cryptocurrency taxation framework, introducing a 10% capital gains tax and a separate 15% levy on income generated through staking and decentralized finance (DeFi).
The legislation passed on November 5, 2026, with the main provisions scheduled to take effect on January 1, 2027.
The framework establishes clearer taxation rules for cryptocurrency investors, including those trading Bitcoin, Ethereum and other digital assets.
According to the Finance Ministry, the changes aim to integrate cryptocurrency investments into Greece's existing tax system.
The government is expected to publish additional guidance covering reporting obligations, transparency requirements and tax audits.
Crypto Gains Above €500 Face 10% Tax
Individual investors will pay a 10% tax on annual net cryptocurrency gains exceeding €500, approximately $560.
However, the threshold operates differently from a traditional tax-free allowance.
Investors earning €500 or less in annual net gains are exempt, but once their profits exceed that amount, the entire gain becomes taxable.
For example, an investor recording €600 in annual cryptocurrency profits would owe €60 in taxes, rather than paying tax only on the €100 above the threshold.
The rules also apply when investors use cryptocurrency to purchase goods or services.
This means spending Bitcoin or other digital assets can trigger a taxable event, even without converting the cryptocurrency directly into euros.
Staking and DeFi Income Taxed at 15%
Greece will introduce a separate 15% tax on cryptocurrency income generated through staking, lending and DeFi liquidity provision.
These earnings will be classified as interest income rather than capital gains.
The distinction means investors receiving rewards from staking Ethereum or providing liquidity to decentralized protocols may face a higher tax rate than those selling cryptocurrencies for profit.
Meanwhile, investors recording annual cryptocurrency losses exceeding €500 can carry those losses forward for five years.
Eligible losses can offset future cryptocurrency gains, potentially reducing tax obligations during profitable years.
However, the losses cannot generally be used to reduce taxes on unrelated income.
Investors Get 12 Months to Declare Past Crypto Gains
The legislation introduces a 12-month voluntary disclosure period, allowing investors to report previously undeclared cryptocurrency gains without late-filing penalties or interest.
Participants must satisfy the applicable conditions and pay the resulting tax within 60 days of submitting their declarations.
The measure is intended to encourage compliance while bringing previously unreported cryptocurrency activity into the tax system.
However, uncertainty remains regarding cryptocurrency-to-cryptocurrency transactions.
The Finance Ministry maintains that swapping one cryptocurrency for another should not trigger capital gains taxation.
Parliament's Scientific Service has warned that the legislation's broad wording could potentially include such exchanges.
Further clarification may therefore be necessary, particularly for transactions involving stablecoins and other digital assets.
Greece Moves Toward Clearer Crypto Tax Rules
The new legislation represents a significant regulatory development for Greece's cryptocurrency market, where determining the tax treatment of digital assets has previously been challenging.
Unlike the European Union's broader cryptocurrency regulatory framework, individual member states maintain different approaches to taxing investment profits.
According to Reuters, cryptocurrency tax rates across European countries generally range from 8% to 30%.
Greek authorities have not yet estimated the revenue expected from the new rules, partly because many domestic investors use overseas exchanges.
The 2027 framework provides clearer tax obligations for investors, although implementation guidance and unresolved questions about crypto swaps remain important.


