
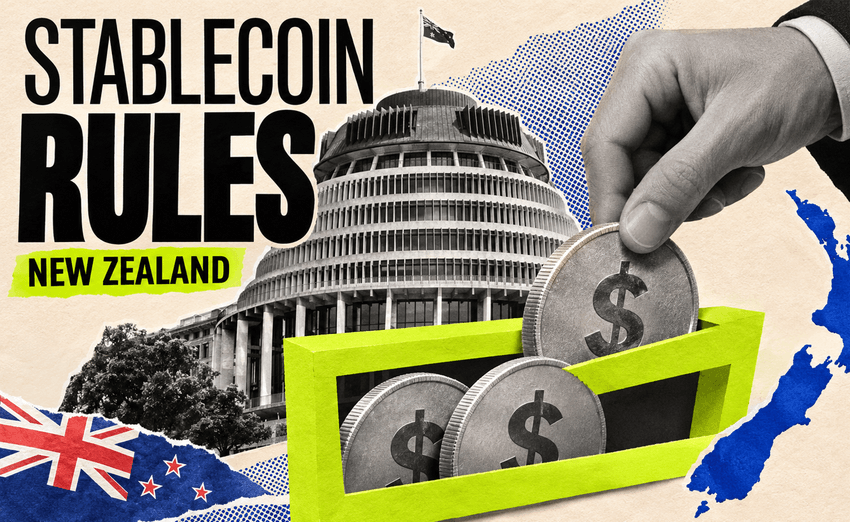
New Zealand's Financial Markets Authority (FMA) has launched a consultation on new stablecoin rules, aiming to create a clearer regulatory framework for digital currencies backed by the New Zealand dollar.
The consultation opened on November 9, 2026, and focuses on stablecoins designed primarily for payments rather than investment.
Under the proposal, qualifying NZD-backed stablecoins would not be classified as financial products under the Financial Markets Conduct Act 2013.
The move could reduce regulatory uncertainty for local issuers while maintaining protections for customers holding digital assets.
However, the proposal has not yet been adopted, and the FMA is seeking industry feedback before making a final decision.
Stablecoins Must Meet Strict Reserve Requirements
The proposed framework would apply only to stablecoins meeting specific financial safeguards, including full backing by New Zealand dollars.
Issuers would need to hold reserves at a New Zealand-registered bank, with the money maintained on trust for token holders.
Each stablecoin must also be redeemable at its face value, ensuring that holders can exchange their tokens for the corresponding amount of NZD.
Additionally, qualifying stablecoins would not be permitted to generate returns for holders, distinguishing payment tokens from investment products.
Issuers would face ongoing obligations, including public reporting on their reserves.

The regulator believes clearer rules could support innovation without undermining confidence in New Zealand's financial system.
NZDD Stablecoin Struggles Despite Regulatory Approval
The consultation follows difficulties facing NZDD, New Zealand's most prominent locally issued stablecoin.
Earlier in 2026, the FMA determined that NZDD, issued by ECDD Holdings Limited, did not qualify as a financial product.
The decision recognized that the token was fully backed by NZD held in trust and did not provide investment returns.
Despite receiving regulatory clarity, NZDD reportedly struggled to attract widespread adoption, with its circulating supply declining nearly 50% since August.
Meanwhile, Easy Crypto's Australian parent company, Swyftx, closed its New Zealand exchange operations on March 31.
The company subsequently sought a buyer for the NZDD stablecoin business.
The challenges illustrate that regulatory approval alone does not guarantee commercial demand for digital payment products.
New Zealand Looks to Simplify Crypto Regulation
New Zealand currently lacks a dedicated stablecoin licensing framework, leaving issuers to navigate existing financial services legislation.
The FMA's proposal would introduce a broader classification approach rather than requiring each qualifying stablecoin to obtain an individual regulatory determination.
The regulator previously acknowledged industry concerns about uncertainty, compliance costs and complicated licensing requirements.
Of 24 companies applying to its December 2024 fintech pilot, only six were admitted, with NZDD reportedly the only participant to reach the market.
The new approach is intended as an interim solution while broader digital asset regulations remain under development.
Australia and Hong Kong Lead Regional Stablecoin Regulation
New Zealand's consultation comes as several Asia-Pacific jurisdictions advance their own stablecoin frameworks.
Australia regulates certain payment stablecoins through financial services requirements, while Hong Kong has introduced a dedicated licensing regime.
Singapore has also been developing legislation addressing stablecoin issuers and payment services.
These developments highlight growing regulatory attention toward digital currencies intended for everyday transactions.
The FMA is accepting public submissions until December 18, 2026, after which it will review the feedback and decide whether to implement the proposed designation.
The regulator has emphasized that no final decision has been made.
For now, New Zealand is exploring a clearer route for domestic stablecoin issuers, potentially making NZD-backed digital payments easier to develop while preserving reserve and redemption safeguards.


