
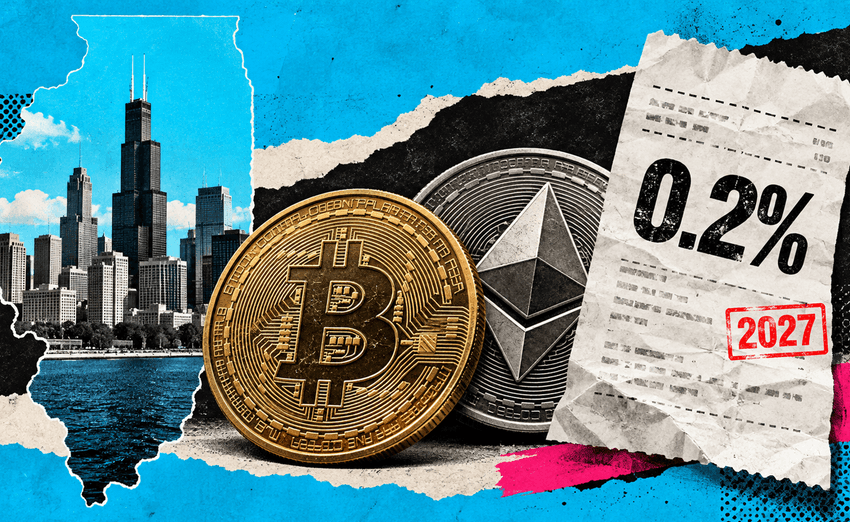
Illinois is preparing to implement a 0.2% tax on certain digital asset business activity, creating a state-level charge that differs significantly from traditional capital gains taxation.
The Digital Asset Tax Act was enacted as part of SB 3019, which Governor J.B. Pritzker approved on June 16. The legislation passed the Illinois House 73–41 before the Senate concurred with the House amendments 36–19. The new digital asset tax takes effect on January 1, 2027.
Unlike a capital gains tax, the levy is calculated on the value of the digital asset involved in the covered activity, rather than the investor's profit.
That means the tax can apply even when a customer has not made money on the underlying crypto position.
Tax Extends Beyond Buying and Selling
The law imposes the tax on the privilege of receiving covered “digital asset business activity” from a digital asset broker in Illinois.
Its definition is broader than ordinary crypto trading. Covered activity includes individual occurrences of exchanging, transferring or storing digital assets when those services are provided as part of a business relationship with a customer.
Transfers can include moving assets between accounts belonging to different people, moving assets between accounts or storage belonging to the same customer, or relinquishing custody or control to another person. Storage includes holding or maintaining custody or control of digital assets for customers.
The 0.2% charge is collected by the digital asset broker making or facilitating the covered transaction. The statute also states that the levy comes in addition to other applicable Illinois or local occupation and privilege taxes.
This makes DATA structurally different from federal taxation of cryptocurrency gains, because the Illinois charge focuses on transactional activity and asset value rather than realized investment profits.
Crypto Industry Pushes Back
The law has generated opposition from parts of the cryptocurrency and venture capital industries, which argue that transaction-based taxation could make operating in Illinois more expensive for digital asset companies and their customers.
Critics have particularly focused on the fact that the levy can apply regardless of whether the underlying investment generated a profit or loss.
The legislation's breadth also means businesses may need to evaluate activities beyond straightforward purchases and sales, including custody and asset transfers, when determining their tax obligations.
Supporters of the measure have instead argued that digital asset businesses should contribute tax revenue when providing services to customers in the state. The final statute establishes the tax as part of Illinois's broader revenue framework.
Lawmakers Introduce Bill to Repeal the Tax
Opposition has also moved into the Illinois legislature.
Representative John Cabello introduced HB 5798 on June 22, just six days after Pritzker approved SB 3019. The bill is straightforward: it would repeal the Digital Asset Tax Act entirely and take effect immediately if enacted.
The repeal effort has since attracted additional sponsors. However, as of late September, the General Assembly's official record shows HB 5798 as filed in the House, not enacted into law.
Unless lawmakers repeal or amend DATA before its implementation date, the 0.2% tax is scheduled to begin January 1, 2027.
Losing Trades Can Still Trigger the Tax
The structure of the levy creates one of its most consequential differences from ordinary investment taxation.
If an investor sells cryptocurrency at a loss, there may be no capital gain on which to impose a conventional gains tax. But a qualifying transaction facilitated by a covered digital asset broker can still be subject to Illinois's 0.2% levy because it is based on the asset value connected to the service.
The same distinction potentially matters for frequent traders, where relatively small charges can accumulate across repeated covered activities.
Illinois has therefore created a crypto tax model that focuses less on an investor's final economic return and more on the gross value of digital asset business activity received by customers.
With implementation approaching in January, attention will now turn to how the state interprets the law in practice-and whether the growing legislative effort to repeal DATA gains enough support to change the framework before the first 0.2% taxes become due in 2027.


