
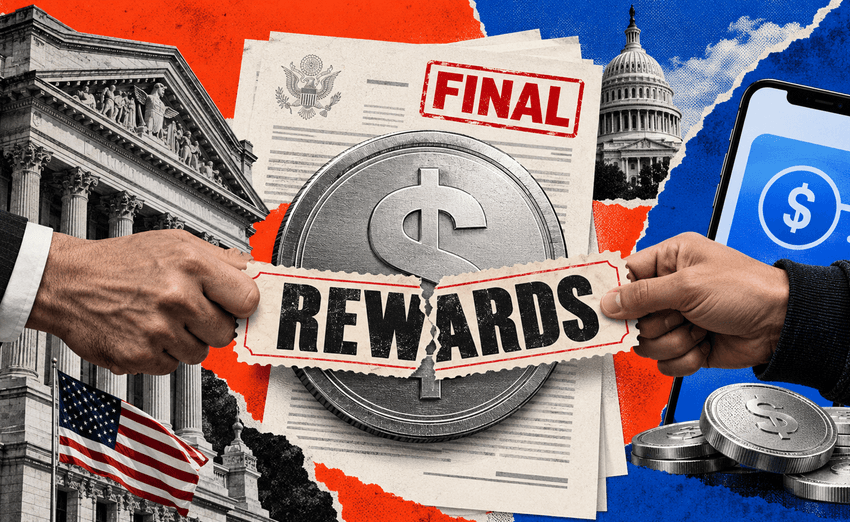
The Office of the Comptroller of the Currency (OCC) has finalized new stablecoin regulations under the GENIUS Act, triggering disagreement between traditional banking organizations and cryptocurrency industry representatives.
Announced on October 21, 2026, the rules clarify how stablecoin rewards offered through third-party platforms will be evaluated.
While the legislation prohibits stablecoin issuers from directly paying interest to holders, rewards distributed through exchanges and other intermediaries remain subject to regulatory interpretation.
The final rule removes an earlier presumption that certain third-party reward arrangements violate the law.
Instead, regulators will evaluate individual arrangements based on their structure and circumstances.
The regulations are scheduled to take effect on January 18, 2027.
US Banking Groups Warn About Deposit Outflows
Three major American banking organizations criticized the OCC's decision, arguing that stablecoin rewards could encourage customers to move money away from traditional bank deposits.
American Bankers Association CEO Rob Nichols accused the regulator of undermining congressional efforts to protect the banking industry's lending capacity.
The ABA also warned that reward-bearing stablecoin products could create confusion between regulated bank deposits and digital assets.

She argued that uncertainty surrounding third-party rewards could expose banks to additional deposit competition.
Meanwhile, Independent Community Bankers of America CEO Rebeca Romero Rainey called for stronger protections for community banks, emphasizing their importance in financing local businesses and households.
Banking representatives argue that reduced deposits could eventually limit lending activity.
OCC Removes Presumption Against Third-Party Rewards
The dispute centers on how the GENIUS Act's prohibition on stablecoin interest payments should apply to intermediaries.
Under the legislation, stablecoin issuers cannot directly offer interest or yield simply for holding their tokens.
However, cryptocurrency exchanges and payment platforms may provide separate incentives to customers.
The OCC's February proposal would have presumed certain arrangements unlawful unless companies demonstrated otherwise.
The final rule removes that presumption, allowing regulators to examine individual cases rather than automatically treating particular reward structures as violations.
Nevertheless, the OCC retains authority to challenge arrangements designed to circumvent the prohibition on issuer-paid interest.
The decision does not establish unrestricted permission for every stablecoin rewards program.
Crypto Industry Welcomes Regulatory Flexibility
Cryptocurrency advocacy groups welcomed the OCC's revised approach, arguing that it better reflects Congress's intended regulatory framework.
Blockchain Association policy chief Lindsay Fraser supported the changes, suggesting they could encourage additional dollar-backed payment activity under federal oversight.
Industry supporters maintain that third-party incentives should not automatically be treated as prohibited issuer interest payments.
However, regulatory uncertainty has not disappeared.
TD Cowen analyst Jaret Seiberg warned that future regulators and courts could interpret permissible reward arrangements differently.
Consequently, cryptocurrency companies may still face legal uncertainty when developing stablecoin incentive programs.
Banks and White House Disagree on Lending Risks
The disagreement extends to competing estimates of stablecoins' potential impact on bank lending.
The Independent Community Bankers of America estimates that widespread stablecoin adoption could reduce community bank lending by at least $850 billion.
However, that figure is a projection rather than an observed loss.
A separate White House Council of Economic Advisers study estimated that prohibiting stablecoin yield would increase bank lending by approximately $2.1 billion, while creating an estimated $800 million welfare cost.
The studies examine different scenarios and assumptions, making their conclusions unsuitable for direct comparison.
Research from the Bank for International Settlements also indicates that stablecoins and traditional deposits can compete for funds.
However, it does not establish that either projected lending impact will materialize.
Stablecoin Rules Could Influence Global Adoption
The OCC's decision could have implications beyond the United States, particularly as dollar-backed stablecoins expand internationally.
Circle CEO Jeremy Allaire recently outlined plans to enter approximately 40 emerging markets, citing demand across Asia, Africa, Latin America and the Middle East.
As stablecoins become more widely used for payments and savings, competition between banks and digital asset providers may intensify.
The January 2027 implementation will establish an important regulatory framework, although disputes over third-party rewards could continue.
For now, the OCC has chosen case-by-case oversight rather than a broad presumption against stablecoin rewards, leaving banks and cryptocurrency companies divided over the consequences.


